Industries / Finance and business services
Insurance
The insurance industry collects payments from many people and firms into a shared pool, sets the price of each one's risk, and pays from the pool those who suffer a covered loss.
1347
A merchant contract written in Genoa covered losses at sea. The historian Geoffrey Clark calls it the first surviving example of the marine insurance policies that Italian merchants then carried across the Mediterranean and into northern Europe.
33
Milestones achieved across 6 domains.
6
To watch for: announced, not yet confirmed outside.
12
Open deliverables. Nobody has shipped them.
In one minute
Where it started
The oldest surviving insurance contract, written in Genoa in 1347, covered a voyage. In London, fire insurance began in the years after the Great Fire of 1666, and from the 1680s underwriters met at Edward Lloyd's coffee house to insure ships. In 1693 Edmond Halley published a table of deaths by age, and from 1762 the Equitable Society charged for life insurance by age.
Where it stands
Insurers price risk from data, sell through agents, brokers, phones, websites, banks and phone networks, and pass their largest risks on to reinsurers and, since 1997, to investors through catastrophe bonds. Since Hurricane Andrew in 1992, computer models of disasters have guided prices and capital, and an outside check found that the models' losses often ran low. AI agents now read submissions and settle small claims, but the speed figures come from the companies that run them.
What is open
Much of what the industry runs on is public only in pieces, or not at all: rate filings, claims counts, model tests, the record of which disaster policies paid. The open jobs below build public tables, test sets and answer keys from public or made-up data, so that anyone can check a price, a claim decision, an AI tool or a model. Each can be started this month with public data, open-source software and current AI models.
Domains
AchievedWatch forOpen
Domain
Progress
Last achieved
Watch for
Open
Pricing and underwriting
Deciding whether to accept a risk, on what terms, and at what price; the deciding is called underwriting.
7 · 1 · 2
Last achievedLoyalty penalty banned2022
Watch forQuotes from email in seconds
2
openSelling policies
Getting policies to buyers through agents and brokers, by phone, online, through banks and phone networks, and lately through AI assistants.
4 · 1 · 2
Last achievedMis-sold cover repaid2011
Watch forQuotes inside ChatGPT
2
openIn depthInsurance brokerage
Paying claims
Checking a reported loss against the policy and paying it, from a single broken window to a city flattened by a storm.
5 · 1 · 2
Last achievedPandemic cover tested in court2021
Watch forAgents settle small claims
2
openFighting fraud
Finding claims and applications that are invented, staged or inflated, and the people behind them.
5 · 1 · 2
Last achievedFewer frauds, larger sums2025
Watch forPhotos proven at capture
2
openModeling catastrophes
Using computer simulations of thousands of possible storms, floods and earthquakes to estimate what disasters could cost before they happen.
5 · 1 · 2
Last achievedAn open model engine2018
Watch forStorms drawn by AI
2
openReinsurance
Insurance for insurers: an insurer passes part of its risk, and part of the premium, to a reinsurer or to investors, so that one disaster does not break it.
7 · 1 · 2
Last achievedRecord year for disaster bonds2025
Watch forInsuring AI mistakes
2
openIn depthReinsurance
Other narrower industries
InsurTechSurety bondsClaims adjusting
Figureheads
4 people
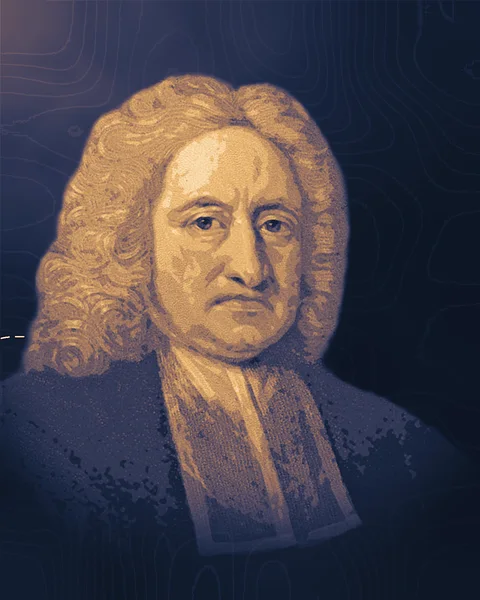
Edmond Halley
1656–1742
He turned five years of one city's birth and burial records into a table of survivors by age, and showed how life insurance and annuities could be priced from it.
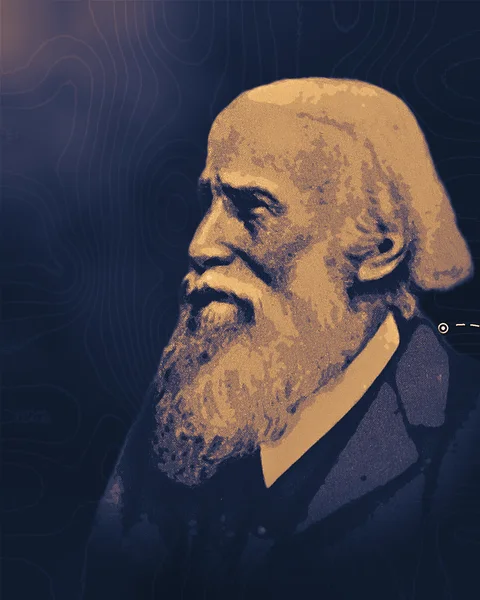
Elizur Wright
1804–1885
As one of Massachusetts's first insurance commissioners he made the state value every life insurer's reserves each year and pushed through America's first law against the forfeiture of lapsed policies.
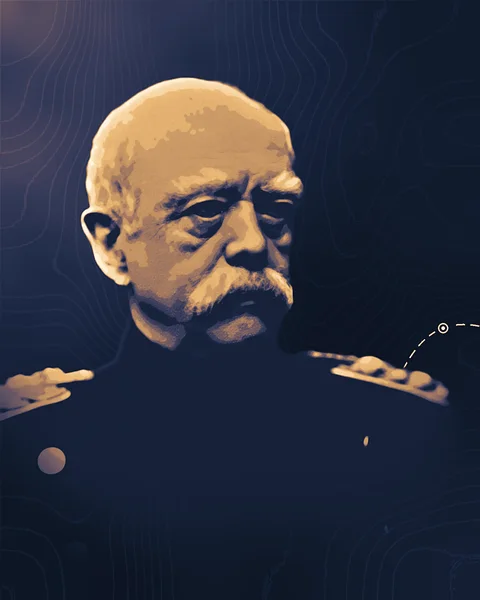
Otto von Bismarck
1815–1898
As German chancellor he drove through the laws of 1883, 1884 and 1889 that made insurance against sickness, accidents at work, disability and old age compulsory for workers, paid for by contributions, the model of social insurance that Germany and many other countries still follow.
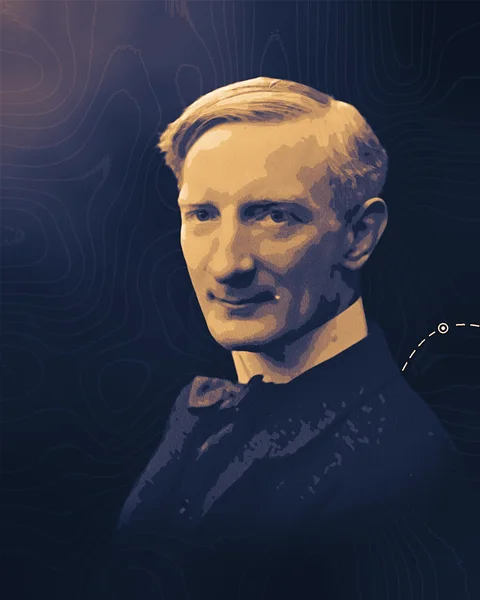
William Beveridge
1879–1963
He helped draft Britain's unemployment insurance law of 1911 and wrote the 1942 report that made flat-rate national insurance, paid for by contributions and paid out without a means test, the plan for Britain's post-war social security.
Open in insurance
3 of 12 open deliverables
Open · Pricing and underwriting
Car-pricing factors in public
A free table that shows, for the ten largest car insurers in five US states, how much each filed rating factor moves the premium for one standard driver. Factors include age, credit-based insurance score, years licensed, home ZIP code and past claims. Each number links to the page of the rate filing it came from.
Built with what exists
state insurance department filing portals and SERFF Filing Access, downloaded by hand within each site's terms; a language model such as Claude or Gemini to read rate manuals and fill the table, citing the page for each value (see the Note "Seven more flagged"); Python and pandas to compute how much each factor changes the price.
Open · Selling policies
A flood policy answer key
300 questions a homeowner might ask about the US National Flood Insurance Program's Standard Flood Insurance Policy, such as whether a freezer in the basement is covered. Two people answer each question separately from the policy text and cite the clause; their agreed answers become the key for scoring AI assistants.
Built with what exists
the Standard Flood Insurance Policy forms and the NFIP Claims Manual, both published by FEMA; current AI models such as Claude, Gemini and ChatGPT; a short scoring script.
Open · Paying claims
Car damage priced from photos
A public answer key for repair estimates: damaged cars photographed to a fixed shot list, each paired with the final itemized invoice from the body shop that fixed it. Anyone can then score a photo-estimating AI in dollars.
Built with what exists
phone cameras; invoices shared with each owner's written consent, with plates, names and addresses removed; vision-capable AI models such as Claude, Gemini and GPT; CarDD for trial runs.